
Our new marketing tagline is “Systematic Outperformance.” Tony came up with it last week and I love it. Apparently he’s not just a pretty face. But he also said something else on the podcast this week that’s worth drilling down on.
When it comes to investing, the mistake I think a lot of us make is thinking like this: if a strategy actually beats the market, it should beat the market every year. And if it has a flat year, or a bad year, then something must be broken. Time to change it, tinker with it, or bail out and go back to tips from the bloke at the barbecue or that seminar I saw advertised on Facebook.
That’s human nature. We want the graph to always go up and to the right in a nice smooth line, every quarter, forever and ever, amen. And the whole finance industry feeds the fantasy, because “consistent outperformance” sells a lot better than the truth.
Here’s the truth. Outperformance is lumpy.
Maybe “Lumpy Outperformance” is even better than “Systematic”, but it probably isn’t as marketable. Anyway, I digress.
Let me show you what I mean with our own numbers, because we publish them and you can check them on our website.
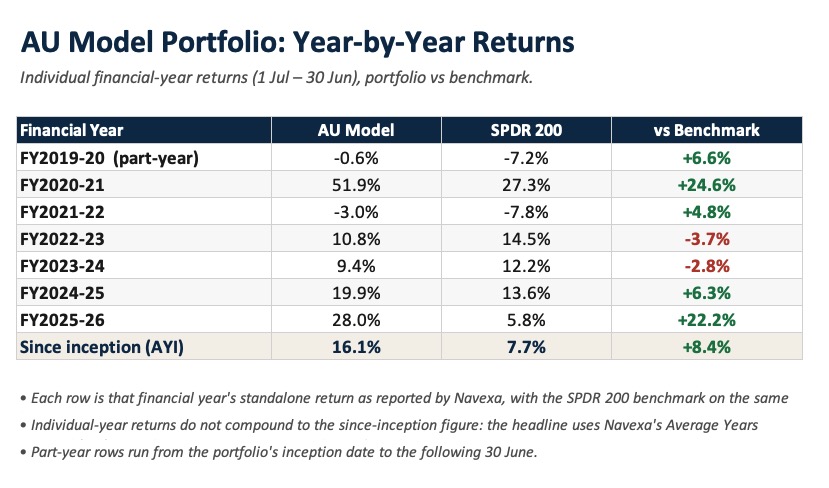
The QAV AU Model Portfolio (formerly known as the Dummy Portfolio) has been running since April 2019. Over those seven financial years it’s returned about 16.1% a year, against the SPDR ASX 200’s 7.7%. Better than double the market. That’s the “Systematic Outperformance” the tagline is talking about, and it’s real and it’s verifiable.
But look under the bonnet and it’s anything but smooth.
Take FY2022-23 and FY2023-24. The index ran 14.5%, then 12.2%. We did 10.8%, then 9.4%. Two years running we didn’t just have a boring year — we lost to the market. By 3.7 points, then 2.8. Two straight years following the exact same rules that had thrashed the index the year before and would thrash it again the year after. That is what lumpy looks like, and it does not feel like a system working. It feels like a system broken.
If you’d thrown in the towel at the end of that second losing year — and plenty did — you’d have walked away right before FY2025-26, when the Model Portfolio did 28% against the market’s 5.8%.
That’s what most years look like. A little bit in front. Sometimes a little bit behind. And then, every few years, the market hands you a blackjack.
This financial year just gone was one of the good hands. The seven gods were good to us this year (yes, I’m watching House Of The Dragon). Members have been emailing their FY26 results and some of them are ridiculous. Jim up 74.5%. Scott up 26.6%. Daryl up around 34% and his win-loss ratio jumped from 55/45 to 70/30. Tony rolled off 17.5% against an STW that did about 5.8%, so nearly triple market. These are not average years. These are the fish you catch once every few seasons.
The mistake is thinking those years are the normal ones and the flat years are the failures. They aren’t failures, they are the normal years.
My favourite example is Ed. Ed’s been with us since the dark ages and he wrote in this week with the first genuinely happy email I’ve had from him in years. His run: down 4.5%, then up 8.3%, then up 3.7%, then up 13.3%, then up 15.5% this year. Look at those first three numbers. Years of just keeping pace, or worse. If Ed had quit after year three — and plenty of people did — he’d have locked in the mediocre part and missed the part that made it all worthwhile. As he put it, it’s easy to stay faithful when everything’s green. It’s hard when it goes red and Rule 1 keeps triggering week after week.
As TK said on the show: You don’t get dealt blackjack every hand. You can’t sit out the boring cards and stroll back to the table only for the good one. You have to play every hand the way the rules tell you to, so that you’re still sitting there when the good one comes. The system Tony designed stops us from losing capital during those years. It keeps us at the table, patiently playing hands, waiting for vingt-et-un. Because you never know when the blackjack year is going to start.
And that’s something most of the professional investors can’t do, and it’s our edge.
According to SPIVA’s Australia scorecard for the year ended December 2025, 74% of active Australian equity funds underperformed the ASX 200 that year. Over the full decade, a solid majority underperformed in every category. Get paid a fortune to trail the index. Nice work if you can get it.
Part of the reason is structural, and it’s the same lumpiness we’re talking about. When a fund has a flat or down year, its investors panic and pull their money out. The manager is forced to sell into weakness to fund the redemptions — and, as Tony points out, the down year is very often the year right before the big one. They get liquidated out of their own recovery.
You don’t have that problem. You can sit through the average years and be there for the blackjack. But you’ve gotta have the cojones to stick it out.
So when we say “Systematic Outperformance,” don’t read it as “we beat the market every single year.” Read it as this: follow the rules through the boring hands, and the math compounds to roughly double the market over time.
The system doesn’t promise you a good hand every deal. It promises that if you keep playing the way the rules tell you to, you’ll still be sitting at the table when the good hands come around.
QAV Myth Killers is a weekly column in the QAV newsletter, taking apart a piece of
investing conventional wisdom. Read the series, or
get it by email every Friday.
General advice only. Spacecraft Publishing Pty Ltd
trading as QAV is a Corporate Authorised Representative (CAR 001292718) of MF & Co.
Asset Management Pty Ltd (AFSL 520442). This is general information and does not take your
personal circumstances into account. See our
disclosure.