
Have you ever heard of The Cobra Effect? No, not the 80s metal band I just made up in my imagination.
The name was coined by economist Horst Siebert in 2001, based on an historically dubious anecdote taken from the British Raj.
According to the story, the British government, who were apparently more concerned about the number of venomous cobras in Delhi than the great famine of 1876, offered a bounty for every dead cobra.
At first, this strategy seemed to work. Large numbers of snakes were killed for the reward. Quite quickly, however, the Indian people being cunning business geniuses, they began to breed cobras for the income.
When the government became aware of this, the reward program was scrapped… and I’m sure you can guess what happened next.
The cobra breeders set their snakes free, leading to an overall increase in the wild cobra population.
This is what is known in economics as a ‘perverse incentive’.
An incentive structure with undesirable, unexpected, and unintended results that can often be contrary to the intentions of its designers.
Unfortunately, an investigation in 2025 by the Friends of Snakes Society cast doubt on the historicity of Siebert’s anecdote.
Their investigation found no contemporary records of cobra breeding operations or prosecutions in British India, and traced the story to an 1873 newspaper article that used speculative language, it was alleged, rather than confirmed evidence.
But there are lots of other examples of this from history that have more evidence to support them. One is the Great Hanoi Rat Massacre, which should have been the name of a hair metal album in the late 1980s, but in fact occurred in 1902 in Hanoi, Vietnam, then known as French Indochina.
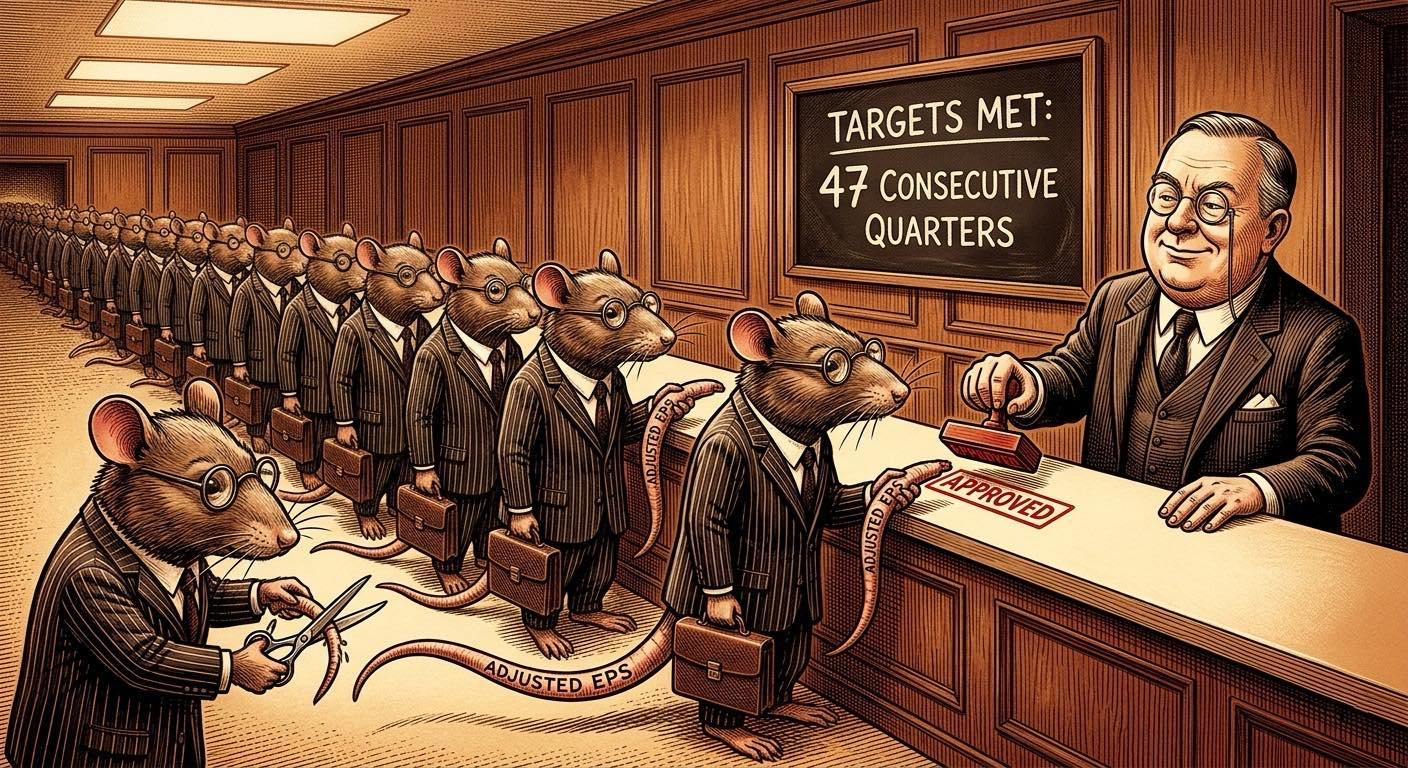
When the French colonial government created a bounty program that paid a reward of one cent for each rat killed, to collect the bounty, people would need to provide the severed tail of a rat.
However, the colonial officials began noticing rats in Hanoi with no tails.
The Vietnamese rat catchers would capture the rats, sever the tails, then release them back into the sewers so they could produce more rats and therefore more tails.
Not learning anything from this, in 2007 the US Army Post Fort Benning in Georgia offered hunters a $40 bounty for every tail of a feral pig they turned in.
During the course of the program, the feral pig population in the area increased.
It turned out that the pigs’ fertility rate and offspring survival rates increased during the scheme, mostly due to the improved nutrition made available by the feed bait used to attract the animals to hunting sites.
On top of that, hunters were found to be more likely to preferentially target large males as trophy quality game while ignoring females and juveniles as targets.
Removing mature males from the population had a negligible impact on population growth because the remaining mature males can each stud many breeding sows.
This effect is similar to Goodhart’s Law, named after Charles Goodhart, the British economist who spent many years at the London School of Economics focusing on central bank governance practices and monetary frameworks.
Goodhart’s Law came from something he said at a conference in Sydney in 1975 that he later admitted was intended as a humorous throwaway line, but it was also perceptive and is cited regularly today in fields ranging from banking to medicine to artificial intelligence because it says something important about how the modern world functions.
What he said was this, any observed statistical regularity will tend to collapse once pressure is placed upon it for control purposes.
In other words, as a British anthropologist later boiled it down, when a measure becomes a target, it ceases to be a good measure.
What does this have to do with QAV?
Well, over the years I’ve heard Tony talk many times about why we don’t use PRICE TO EARNINGS ratio or RETURN ON EQUITY as strong indicators in our system.
The reason being they are two very common metrics used in investing and have been for many decades.
And as a result, companies can often game them and manipulate them to make the share price look more attractive.
One of the main reasons we use price to operating cash flow instead of price to earnings, is because it gets less focus from the investing community and is also harder to manipulate.
QAV Myth Killers is a weekly column in the QAV newsletter, taking apart a piece of
investing conventional wisdom. Read the series, or
get it by email every Friday.
General advice only. Spacecraft Publishing Pty Ltd
trading as QAV is a Corporate Authorised Representative (CAR 001292718) of MF & Co.
Asset Management Pty Ltd (AFSL 520442). This is general information and does not take your
personal circumstances into account. See our
disclosure.