

“Misery loves company, so in light of the latest Bitcoin dump and our return to the 50% drawdown mark, I thought I’d reach out to the other sufferers.” That’s from a post this week by Andrew Page, CEO of Strawman (who was our guest on QAV #355). He wanted to “pour one out for the poor fools among us holding stuff well below recent levels.”
His list: WiseTech down 75%. Pro Medicus down 45%. ARB down 54%. CSL down 58%. Xero down 63%. Cochlear down 60%. Catapult down 50%. Even gold is down 25% from its peak.
Andrew’s point, fair enough, is that these aren’t meme stocks or joke coins. They’re good companies. Real earnings, real products, real market leaders. And he’s not wrong about that.
What makes the list sting more is the timing. This isn’t a crash. The index as a whole is still up for the year and only around 5% off record highs. So while the market parties on, a graveyard of blue-chip growth darlings is quietly getting carried out the back door.
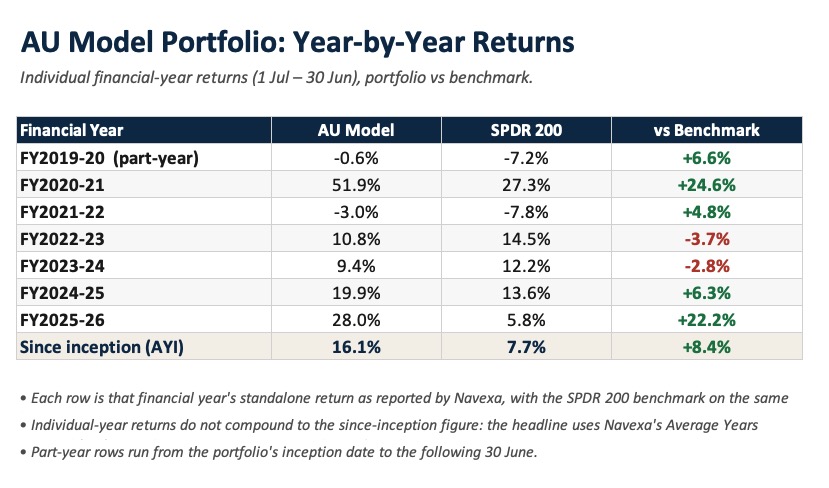
Meanwhile, over on our side of the fence, it’s been the best financial year in QAV’s history. The model portfolio finished FY26 up 28.95%, against 6.61% for the SPDR 200 accumulation index. Better than quadruple the market. Every single one of our four Light portfolios beat the market too, one of them by almost ten times. The stocks doing the damage have names most punters have probably never heard of: Southern Cross Electrical up 508%, GenusPlus up 330%, Duratec up 267%, SHAPE Australia up 134%, and Korvest up 460% since we bought it years ago. Boring, forgettable, cash-generating businesses that most of our own listeners couldn’t tell you what they actually do.
Two portfolios of ASX-listed companies. One full of household names hyped up on every investing forum over the last few years. One full of names even we forget. Guess which one just had its worst year and which one just had its best.
This isn’t really a story about bad companies. It’s the same old story about price.
When Tony talked through the WiseTech-and-friends list on the show this week, he made the distinction plainly: “I don’t disagree with his thesis that they’re good companies… but be a little bit more self-reflective and realise you’re paying way too much for them.” Then the line that’s really the whole article in a sentence: “As it always does, always, every single time, if you overpay for something, it comes back to bite you in the end.”
We wrote about this exact mechanic back in May with Microsoft. Buy the greatest software company on Earth in December 1999 and you’d have waited seventeen years just to get your money back, while the business itself quadrupled its revenue underneath you the whole time. Same law of gravity. Different decade, different postcode, different set of tickers. WiseTech, Pro Medicus, CSL, Cochlear and the rest are this cycle’s Microsoft: businesses that didn’t need to do anything wrong to hand their shareholders a horror stretch, because the price already had years of flawless performance baked into it before a single thing went wrong. A stock priced for perfection doesn’t need bad news to fall. It just needs normal news.
This is the whole reason the QAV checklist puts a hard ceiling on what you’re allowed to pay, regardless of how good the story is. We don’t care how great the business is if the price to operating cash flow is 20 times. It’s off our list well before that. It means we miss the euphoric run-up on the way past. It also means we’re not the ones explaining a 60–75% drawdown to our spouses while the index sits near all-time highs.
Tony made the same point another way a few minutes later, talking about our own good year: “I don’t want to get too hubristic either, because we’ll have a bad year at some stage, and we’ll be in the same boat. But it’ll be for a different reason.” When QAV has a rough year, it’ll be because the whole market fell over… Ukraine, the Strait of Hormuz, whatever the next thing is. It won’t be because we paid 200 times earnings for something we were convinced was going to take over the world.
Our 2019–2026 performance table tells the story about how QAV achieves long-term double market performance. One terrific year, followed by a handful of average years (some a little above, some a little below the benchmark)… and then another terrific year. Rinse and repeat. Stick with the discipline of buying good businesses and obeying the sell triggers.
Good businesses can still be bad investments. It has nothing to do with the quality of the company and everything to do with what you handed over for a piece of it. Andrew’s list isn’t a list of bad companies having a bad run. It’s a list of good companies that got bought at prices that assumed nothing would ever go wrong again.
Something always does.

QAV Myth Killers is a weekly column in the QAV newsletter, taking apart a piece of
investing conventional wisdom. Read the series, or
get it by email every Friday.
General advice only. Spacecraft Publishing Pty Ltd
trading as QAV is a Corporate Authorised Representative (CAR 001292718) of MF & Co.
Asset Management Pty Ltd (AFSL 520442). This is general information and does not take your
personal circumstances into account. See our
disclosure.