
The Myth: You need to understand interest rates, GDP, inflation, central bank policy, and geopolitical trends to invest well.
The Reality: Macroeconomic events have little effect on investing strategy — or returns.
Every week someone asks us a version of the same question. What does Tony think interest rates are going? What does the tariff situation mean for our portfolio? What about the war’s impact on oil prices? Is now a good time to buy given the economic uncertainty?
His honest answer: he has absolutely no idea. And more importantly… he doesn’t care.
Open any financial newspaper / blog / podcast on any given morning and you’ll find the same thing. Analysts predicting what interest rates will do next. Economists forecasting recession or no recession. Fund managers explaining how they’re “positioning” for the macro environment.
It’s an impressive amount of confident noise about things nobody can actually predict.
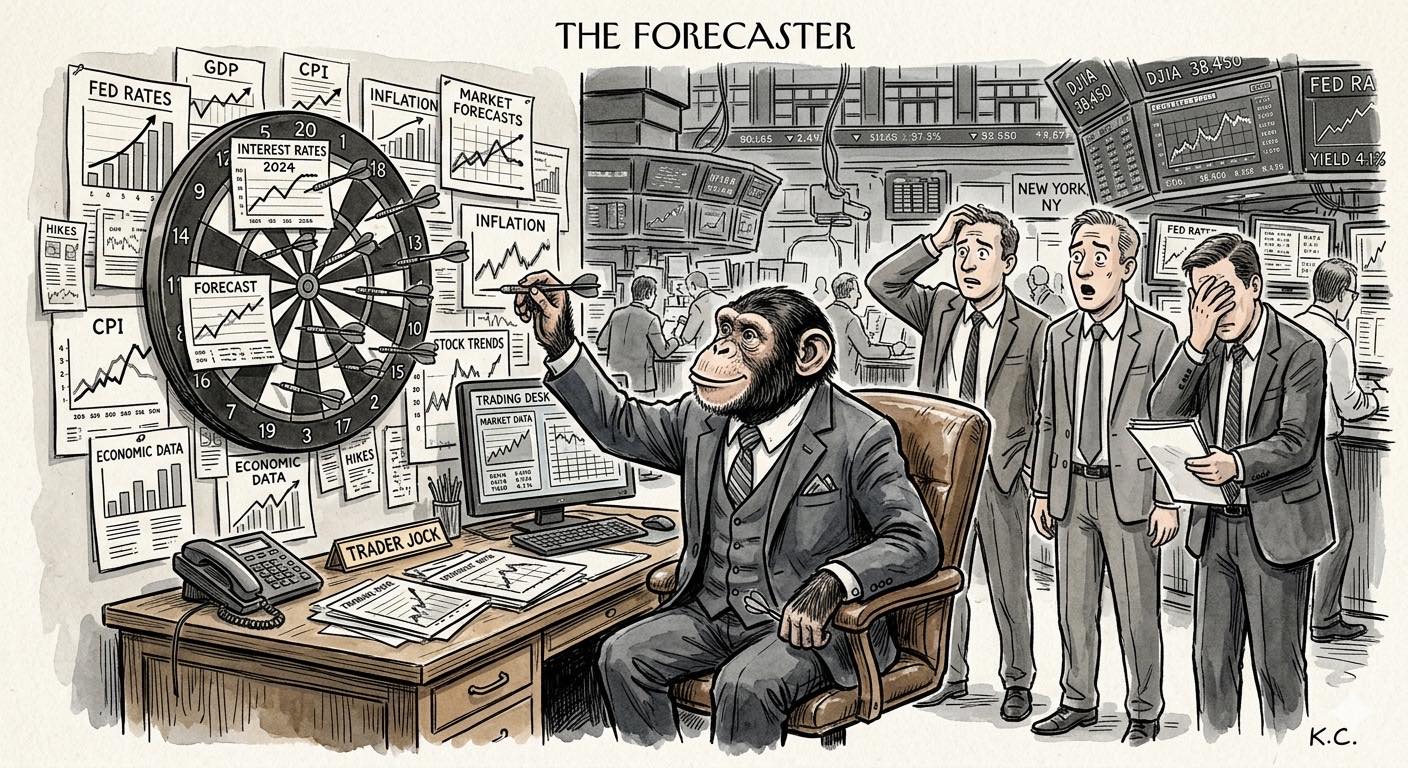
In 2005, Berkeley professor Philip Tetlock published a study of 82,361 expert political and economic forecasts made over twenty years. The experts, including economists, analysts, policy wonks, all performed about the same as random chance. The average expert was roughly as accurate as a dart-throwing chimpanzee.
As he wrote in his follow-up book, “Superforecasting: The Art and Science of Prediction” in 2015:
“Open any newspaper, watch any TV news show, and you find experts who forecast what’s coming. Some are cautious. More are bold and confident. A handful claim to be Olympian visionaries able to see decades into the future. With few exceptions, they are not in front of the cameras because they possess any proven skill at forecasting. Accuracy is seldom even mentioned. Old forecasts are like old news—soon forgotten—and pundits are almost never asked to reconcile what they said with what actually happened. The one undeniable talent that talking heads have is their skill at telling a compelling story with conviction, and that is enough. Many have become wealthy peddling forecasting of untested value to corporate executives, government officials, and ordinary people who would never think of swallowing medicine of unknown efficacy and safety but who routinely pay for forecasts that are as dubious as elixirs sold from the back of a wagon. These people—and their customers—deserve a nudge in the ribs.”
Writing his first book in the early years of the Iraq invasion, he starts off talking about the “intelligence failures” preceding the American invasion and how the experts’ boldest predictions of weapons of mass destruction and of minimal resistance had not been borne out. “What experts think”, he writes, “matters far less than how they think.”
And I think the same is true when it comes to investing. What Tony teaches us, is not what to think about investing, but a way to think about investing. And one of his principles is that nobody — repeat, nobody — can predict the future. So all of this expert opinion about macro economic issues is, largely, a waste of time listening to.
Look — don’t get me wrong. Some forecasters do a better job than others. And macro events do affect markets short-term — we’re not saying it’s completely irrelevant. Severe enough shocks (GFC, COVID, interest rate movements, war and other supply chain issues) genuinely do change company fundamentals. Interest rates affect discount rates and therefore valuations — this is mathematically true. It feels responsible and grown-up to pay attention to the big picture.
But Tetlock’s demonstrated that, on average, expert forecasters have no better than chance over 20 years. Even the RBA and the Fed have to revise their own forecasts dramatically — they don’t seem to have any better idea about what the future holds than the rest of us. As the late American economist Paul Samuelson once famously said: “The stock market has predicted nine of the last five recessions.” Experts have spent years warning about Chinese debt implosion — China kept growing. Ray Dalio’s Bridgewater macro fund has underperformed a basic index for years.
Macro news is the most public information in the world — millions of analysts trade on it instantly. If inflation data drops and you think “I should sell bonds” — that trade happened before you woke up.
The QAV checklist uses publicly available company data for a reason: the edge is in the analysis, not the news.
Our checklist does have a field for “current interest rate environment”, but it’s used purely to measure whether or not the stock might be of interest to investors looking to leverage their portfolio for a dividend, not as a predictor of the future returns of the business. The checklist doesn’t ask: what’s GDP doing? Is a recession likely? It asks: is this company high quality? Is it cheap? Those questions are macro-agnostic. If macro hits a company’s fundamentals, the checklist catches it at the next review — you don’t need to predict it, you just need to measure it.
Tony’s position has been consistent for the seven years we’ve been doing the podcast: he doesn’t know what interest rates will do, he doesn’t know when the next recession is coming, and neither does anyone else. So we don’t pretend otherwise. We check the numbers. We follow the process. We buy quality at a discount and we wait.
The checklist is the answer to the macro question. Not because it predicts macro — but because it doesn’t need to.
Warren Buffett famously ignores macroeconomic forecasts: “If we’re right about the business, macroeconomic factors won’t matter. And if we’re wrong about the business, macroeconomic factors won’t save us.”
The economy is an enormously complicated system that no one fully understands. The QAV checklist is a data-based process that doesn’t need to.
You don’t need to know what the Fed or the RBA will do next. You need to know whether the company you’re looking at passes the checklist. Those are very different questions — and only one of them is answerable.
It turns out the best investing strategy isn’t watching Bloomberg. It’s ignoring it.
QAV Myth Killers is a weekly column in the QAV newsletter, taking apart a piece of
investing conventional wisdom. Read the series, or
get it by email every Friday.
General advice only. Spacecraft Publishing Pty Ltd
trading as QAV is a Corporate Authorised Representative (CAR 001292718) of MF & Co.
Asset Management Pty Ltd (AFSL 520442). This is general information and does not take your
personal circumstances into account. See our
disclosure.