As I’ve probably mentioned, during the last week I’ve been listening to Shostakovich’s Seventh Symphony, aka the Leningrad, over and over. I’ve also been watching a 2016 BBC documentary about the Leningrad première. It’s been called “a legendary moment in Soviet political and military history” and for good reason.
Two questions I’ve been thinking about are: why the hell would you try to put on a concert when people are dying of starvation and a city is under siege? And… what investing parallels can I learn from this story?
Surely “art” could take a back seat during the most brutal siege in history. I’d put “finding food” and “survive the brutal winter” much higher on my list of important things. But it served two important purposes. I’ll get to that in a minute. Let me give some context.
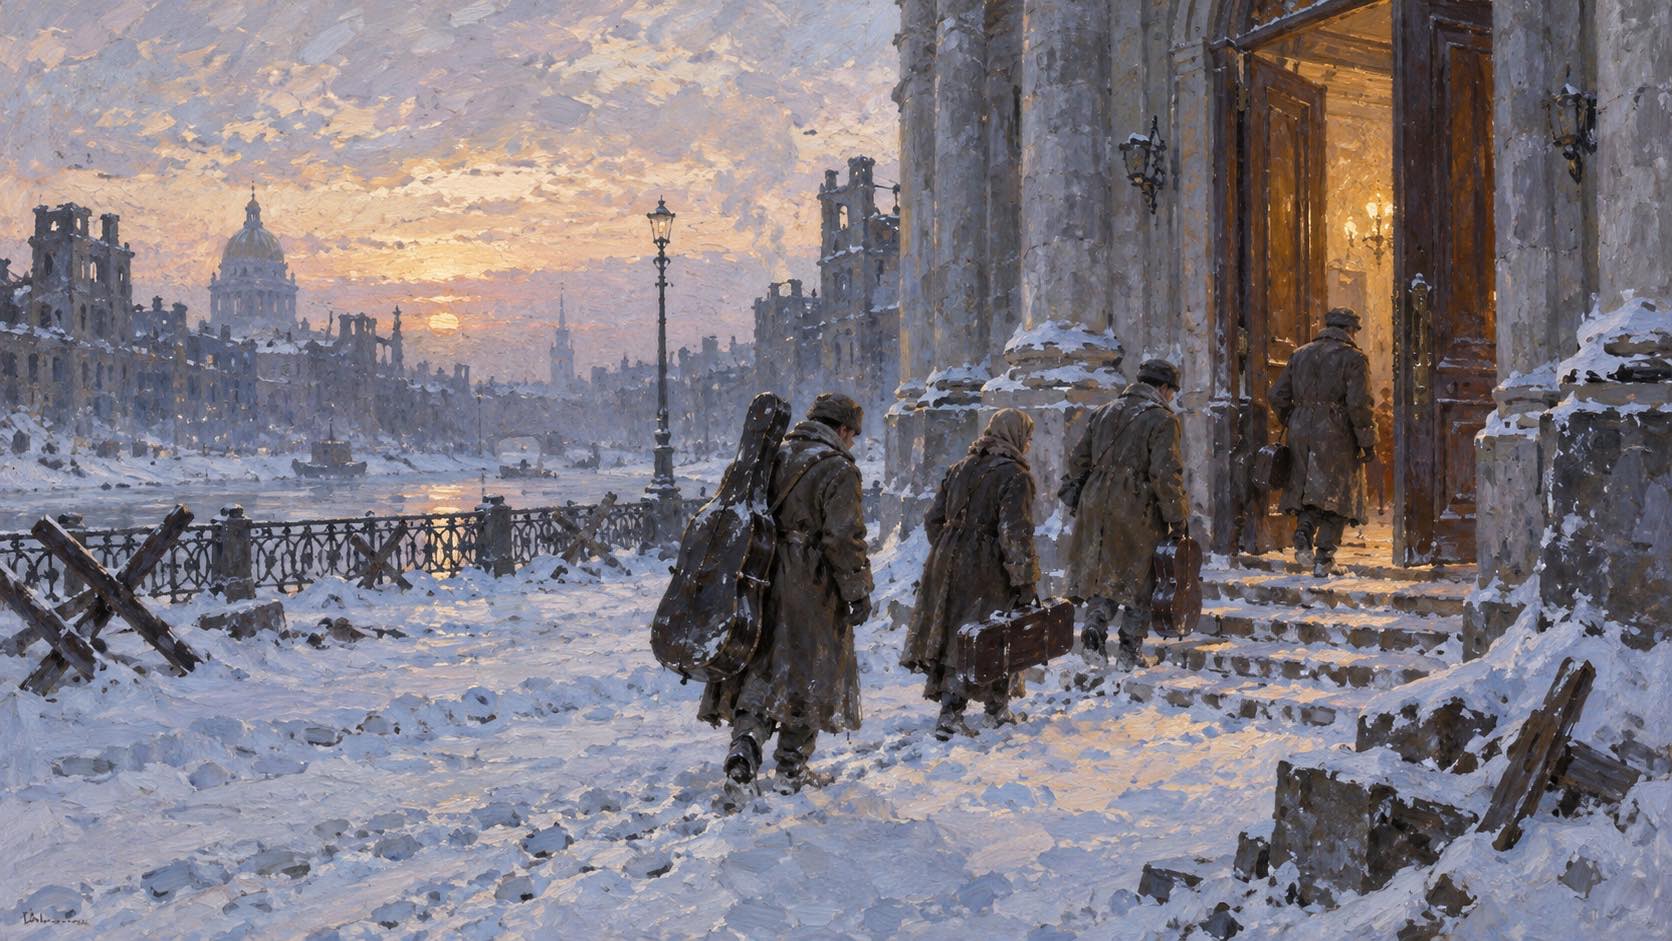
If you don’t know anything about the symphony, here’s the quick version. In 1941, Germany invaded the Soviet Union during the opening stages of Operation Barbarossa and laid siege to Leningrad, now Saint Petersburg and blockaded the city. It lasted 872 days, and an estimated 1.5 million people died out of a population of about three million, many of them from starvation.
Leningrad was Shostakovich’s home town. He and his family were there during the early months of the siege, and he started composing the Seventh Symphony while the city was under attack. He was eventually evacuated and finished it elsewhere in the Soviet Union.
In August 1942, the symphony was performed in Leningrad for the first time. It’s a crazy story. Karl Eliasberg, the only conductor left in the city, summoned the players of his Leningrad Radio Orchestra, only fifteen out of the usual forty members were still available; the others had either starved to death or left to fight the enemy. Eliasberg himself had spent the last few months in hospital recovering from extreme exhaustion and dystrophy caused by malnourishment.
Now, this symphony is massive. It’s designed to be incredibly loud and terrifying, and it needs a huge orchestra of 100 players to perform it properly. So Eliasberg had to find more musicians, literally going door to door to find as many as he could, only to discover many of them suffering from malnutrition. Some were too weak even to rehearse. Others fainted during rehearsals. He used them anyway.
Why bother under these circumstances?
The performance was pertly intended to bolster the morale of the people in Leningrad. As one of the surviving audience members told the documentary in 2016: “There was a sense of pride. Damn you! We have an orchestra, and we’re at the Philharmonic Hall! We were surrounded by Germans, they were shelling us, but there was this feeling of superiority.”
And it was also used as psychological warfare against the German forces surrounding the city. Radio Leningrad set up speakers to broadcast the performance to the German front. “We’re still alive and you haven’t crushed our spirit.” (The message was NOT, as TK suggested on the show this week, “end the siege now, or we’ll play his first six symphonies as well!” Geeeez.….)
After the war, German PoWs supposedly told the Soviets that after hearing the performance many of them had the feeling that they were going to lose the war.
The performance was what you might call “costly signalling”, as opposed to “cheap signalling”. Cheap signalling doesn’t cost you much in time or effort. You just say, “things are going great” and move on.
Actually pulling together an orchestra when the city is starving, and then putting on a concert? People who can barely walk putting on their finest clothes and turning up to hear it? That costs something. They were saying: we’re still here. We can still produce and perform great art.
But, I hear you saying — okay nerd, what does this have to do with investing?
I’ve been thinking a bit this week about costly signalling in value investing. We’ve often heard Tony say over the years that he ignores the stories and looks at the numbers. Of course, the numbers tell a story, too. It’s just a more believable story than the one the CEO will usually trot out. One of the things we’re looking for is whether a company backs up what it says with something that costs it real money or real effort.
Saying that everything is great, business is booming and there are good times ahead is the job of every CEO. But where the rubber meets the road is in the numbers. A costly signal is persuasive when it’s harder for someone who cannot back up the claim to imitate.
It’s one of the reasons we look at the directors’ equity stakes in a business. They might talk a good talk, but how much of their own money have they put into the company’s stock? If you think the company’s future is rosy, sink your own damn cash into the shares. Or take a huge chunk of your compensation as shares.
We also look at how the company spends its own profits.
For example — share buybacks, something we added to the checklist relatively recently. If a company is spending its hard-earned cash to buyback its own stock, it thinks that’s a better use of its funds than, say, dividends, marketing, discount promotions, new offices, acquisitions, or new equipment. Instead, it’s buying its own shares. That’s a kind of costly signal about what it believes the business is worth. Anyone can just say “we’re doing a buyback”. And many do. That’s why we don’t score a buyback unless the share count has significantly diminished.
Another kind of costly signalling is paying down debt. We don’t score businesses for debt specifically, but we do look at measures such as financial health and increasing equity over time. Both relate, in some way, to how much debt the business is carrying.
Then there’s the dividend. A business that keeps paying one during tough times is spending cash it could have used for other things. That can be a signal that it expects better times ahead.
Costly signalling is how companies show us through their actions that they do actually think their stock is worth buying. They aren’t just saying they are doing well. They are putting on a show. Of course, a buyback isn’t remotely the same as putting on a concert while dying of malnutrition. But you get my point. As the old saying goes — “actions speak much louder than words”.
Sidenote: My kung fu abs are also a costly signal. Remind me to show them to Tony on the podcast next week. I think he needs motivation.
QAV Myth Killers is a weekly column in the QAV newsletter, taking apart a piece of
investing conventional wisdom. Read the series, or
get it by email every Friday.
General advice only. Spacecraft Publishing Pty Ltd
trading as QAV is a Corporate Authorised Representative (CAR 001292718) of MF & Co.
Asset Management Pty Ltd (AFSL 520442). This is general information and does not take your
personal circumstances into account. See our
disclosure.
Leave a Reply